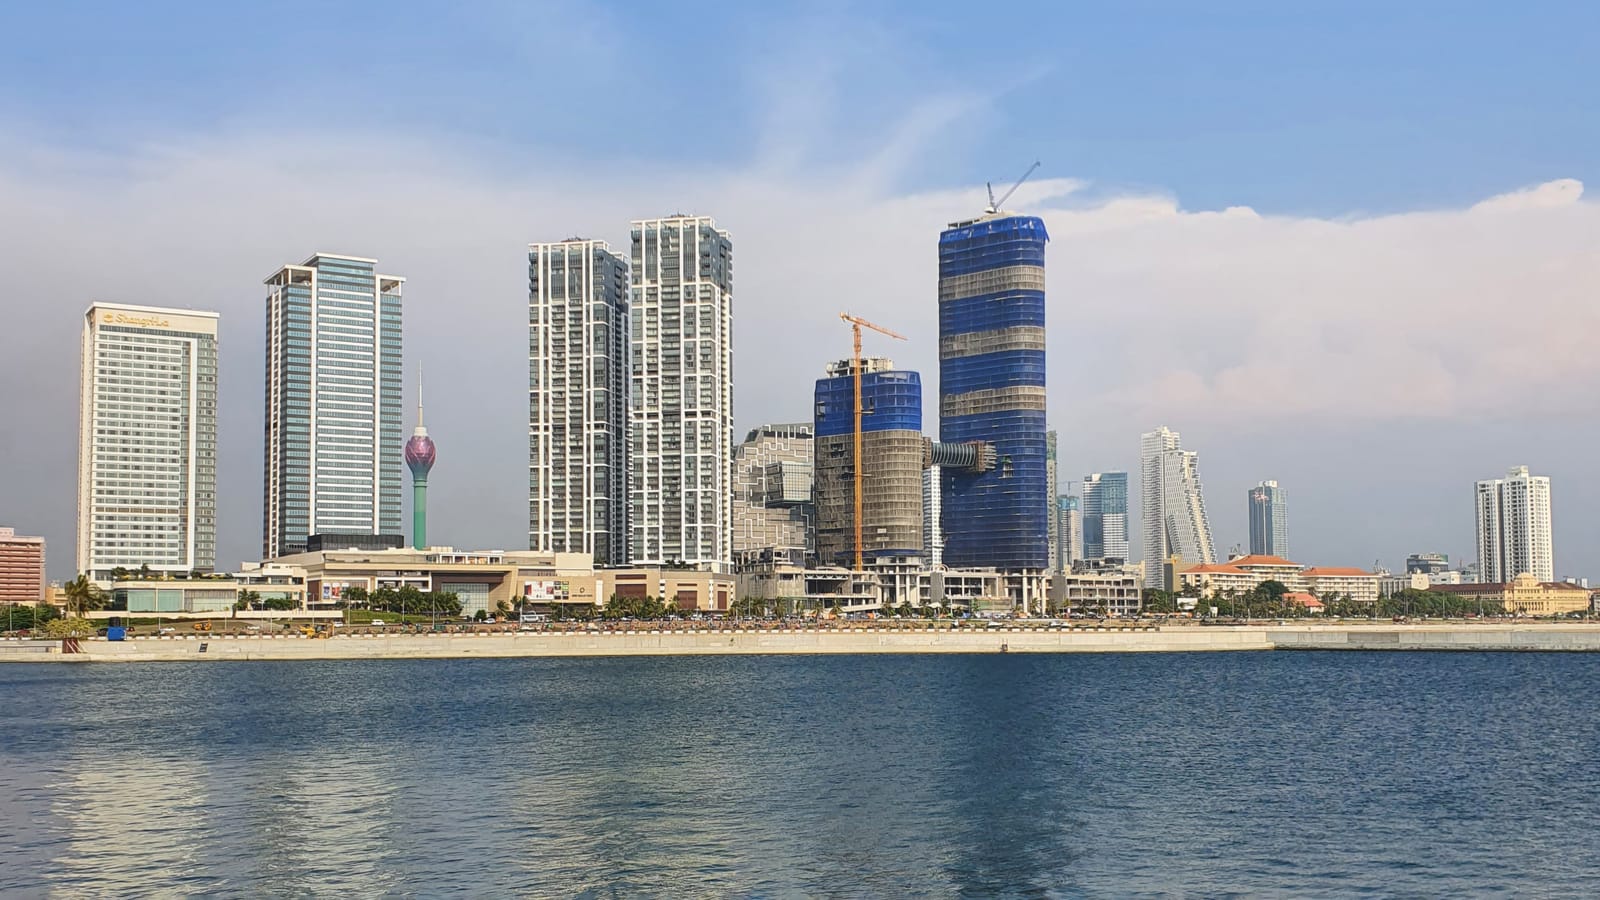
Port City Colombo held its first investor forum in India on 4 November, pitching Sri Lanka’s only foreign currency-designated special economic zone to more than 200 Indian business leaders, investors and policymakers at the Hyatt Regency in Chennai.
The invitation-only event was hosted by the Deputy High Commission of Sri Lanka in Chennai with Port City Colombo, and drew representatives from real estate, financial services, logistics, IT and technology, along with officials of leading Indian industry chambers, the Daily FT reported.
Its theme was “India’s Growth Story, Strengthened: Why Sri Lanka, Why Now” — a pitch framed around Indian firms extending their reach without relocating from their home base. Organisers cited proximity, a shared time zone, cultural similarities and established commercial and legal institutions as practical advantages.
The offer on the table
Deputy Managing Director of CHEC Port City Colombo Thulci Aluwihare set out the zone’s statutory terms:
- a single-window approval process
- defined investor safeguards and a stabilisation mechanism
- international arbitration provisions
- 100% foreign ownership
- the ability to transact in 16 foreign currencies, including the Indian rupee
Discussions ranged beyond real estate into product engineering, treasury operations, data analytics, cybersecurity and business process operations, as well as data centres and AI.
”Certainty of the framework”
Colombo Port City Economic Commission Chairman Harsha Amarasekera, PC put regulatory predictability at the centre of the pitch.
“For investors, the strength of a proposition lies not just in the opportunity it offers, but in the certainty of the framework within which they operate,” he said. Sri Lanka offers Indian business “proximity, familiarity and access to wider regional opportunities… with the centre of growth remaining in India.”
He also described Port City as a project of national importance operating under the direct purview of the Office of the President, Anura Kumara Dissanayake, who is also Finance Minister.
Deputy High Commissioner for Southern India Dr. Ganesanathan Geathiswaran, who opened the programme, said the two countries were “bound by geography, history and commerce,” and named Chennai’s industrial base and entrepreneurial ecosystem as reasons for holding the forum there.
A panel brought together Madhu Raghunath, CEO of TVS Vehicle Mobility Solutions and co-chairman of the Confederation of Indian Industry’s southern region taskforce on international business development, and Robin S., JLL’s senior director and head of its centre of excellence for India and Sri Lanka, alongside Amarasekera and Aluwihare.
“A clear regulatory framework and transparent incentive framework give Port City Colombo the ingredients for serious interest from India, and the conversations thus far show that interest is building,” Robin S. said.
This is the strategy stated in September
The Chennai forum is the execution of a plan this desk reported two months ago. CHEC Port City said in September that it read the Modi–Xi thaw as an opening for Indian investors and had hired a PR firm specifically to improve Indian investor perception of the project. At that point US$2.1 billion was under binding agreement across 15 of 74 marketable lots, against a stated target of a further US$4.1 billion over five years.
Chennai follows earlier roadshows in Dubai, Melbourne and an Oman delegation visit, making India the latest market in a continuing sequence rather than a departure.
Not reported
No filing reports a single commitment, letter of intent or sum of money arising from the forum — the only figure given is attendance. None names an Indian company as a prospective investor beyond the two panellists’ own firms, and none says whether any of the 74 marketable lots is under discussion with Indian buyers.
Nothing explains why Chennai was chosen over Mumbai or Delhi beyond the Deputy High Commissioner’s reference to its industrial base, and no follow-up event or date is announced — the stated next step is only that “continued dialogue will be pursued.”
The filings also leave the US$2.1 billion figure from September un-updated, so it is not possible to say whether Indian investment has moved since.
A note on sourcing and timing. The forum took place on 4 November. Hiru News reported it on 6 November; the Daily Mirror and Daily FT both filed on 10 November, six days after the event. All three accounts reproduce the same organisers’ release — the Daily FT carries it in full with direct quotes, the Daily Mirror an abridged version, and Hiru a reworded one — so although three verified newsrooms carried it, there is one underlying document and no independent reporting. The Daily Mirror’s version carries no reporter byline. No Indian newsroom account was found in verified sources, and no critical or third-party assessment of the pitch has been published.